The Vacation Home Tax Trap: How Casual Rentals Can Trigger Rules That Cost You More Than You Earned
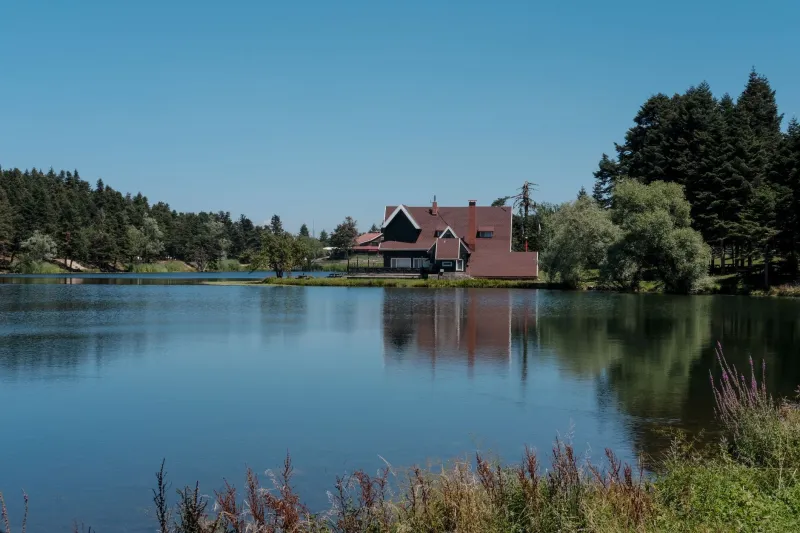
For many Americans, a vacation home represents more than a place to unwind. It is an asset — something that can generate income when you are not using it, appreciate over time, and eventually contribute to long-term financial security. Platforms like Airbnb and VRBO have made casual short-term rentals more accessible than ever, and millions of vacation homeowners now supplement their expenses by renting out their properties for a few weeks each year.
What most of those owners do not realize is that the IRS has a detailed, layered set of rules specifically designed for vacation properties — rules that can determine whether your rental income is taxable, whether your expenses are deductible, and whether you are inadvertently triggering depreciation recapture, passive activity loss limitations, or even self-employment tax exposure. The line between a personal retreat and a rental property is not drawn by your intentions. It is drawn by the calendar.
The 14-Day Rule: Small Number, Large Consequences
At the center of vacation home taxation sits a deceptively simple threshold: 14 days, or 10 percent of the total days the property is rented at fair market value — whichever is greater. This benchmark determines which of three distinct tax regimes applies to your property.
Scenario one is the most favorable. If you rent your vacation home for fewer than 15 days during the year, the IRS does not require you to report that rental income at all. The property is treated as a personal residence, the income is excluded, and the rental expenses are not deductible either. For owners who occasionally rent out a beach house during a high-demand weekend or two, this rule is a genuine windfall — and one that is frequently overlooked.
Scenario two applies when your personal use exceeds the 14-day or 10-percent threshold. In this case, the IRS treats the property as a personal residence with rental activity, and your ability to deduct rental expenses is limited. You can offset rental income with a proportionate share of expenses, but you cannot use those expenses to generate a loss that offsets other income. The allocation itself is complex, requiring you to divide mortgage interest, property taxes, utilities, and maintenance between personal and rental days using IRS-prescribed formulas.
Scenario three is where the most significant tax exposure lies. If your personal use falls below the 14-day or 10-percent threshold, the IRS reclassifies the property as a rental property rather than a personal residence. This opens the door to deducting a broader range of expenses — including depreciation — but it also subjects the property to passive activity loss rules, which can limit when and how you use those deductions.
Fair Rental Value: A Detail That Trips Up Owners
Not every day you spend at your vacation home counts as a personal use day in the IRS's calculation. Days spent performing maintenance or repairs at fair market value do not count. However, days when family members or friends use the property — even if they pay rent — may count as personal use days if they pay less than the fair rental value for that period.
This distinction matters more than most owners appreciate. A generous gesture — letting your adult children use the property for a week at a discounted rate — can quietly inflate your personal use day count and push you from one tax regime into another. If that shift moves you past the threshold that converts your property from rental to personal residence, you lose the ability to deduct losses entirely.
Fair rental value is not a number you define arbitrarily. The IRS expects it to reflect what an unrelated party would pay for comparable accommodations in the same market during the same period. In competitive short-term rental markets, that number can be substantial, and undercharging family members can have real tax consequences.
Depreciation: The Hidden Benefit That Creates a Future Problem
When a vacation property qualifies as a rental under IRS rules, the owner can begin depreciating the structure over 27.5 years using the straight-line method. For a property with a significant building value, this annual deduction can meaningfully reduce taxable rental income.
The problem surfaces at the point of sale. Depreciation deductions reduce your cost basis in the property. When you eventually sell, the IRS recaptures those depreciation deductions as ordinary income, taxed at a maximum rate of 25 percent — separate from and in addition to any capital gains tax owed on appreciation. Owners who have held a rental property for many years and claimed substantial depreciation can face a significant recapture bill they did not anticipate.
For owners who casually drift into rental property status without a deliberate strategy, this recapture liability can arrive as a complete surprise. It is a cost that accumulates invisibly over the holding period and crystallizes at the worst possible moment — during a sale.
Passive Activity Loss Rules and the Real Estate Professional Exception
If your vacation home qualifies as a rental property, the losses it generates are generally classified as passive losses. Under the passive activity rules, passive losses can only offset passive income — not wages, salaries, or business income. For most vacation homeowners, this means that a rental property generating a tax loss on paper provides no immediate tax benefit.
There is a limited exception for taxpayers with modified adjusted gross income below $100,000, who may be able to deduct up to $25,000 in rental losses against ordinary income — provided they actively participate in managing the rental. This allowance phases out completely at $150,000 of MAGI, which means many higher-income vacation homeowners receive no current benefit from rental losses at all.
Taxpayers who qualify as real estate professionals under IRS guidelines — a designation requiring more than 750 hours of real estate activity per year and more than half of all working hours spent in real estate — can treat rental losses as non-passive and deduct them against any income. For most casual vacation homeowners, however, this threshold is out of reach.
Structuring Your Usage Intentionally
The most important takeaway for vacation homeowners is that tax outcomes are not incidental — they are determined by choices made throughout the year. A deliberate approach to how you use, rent, and maintain your property can position you advantageously before a single form is filed.
If your primary goal is simplicity and tax-free income, keeping rental days below 15 per year may be the cleanest strategy available. If your goal is maximizing deductions, minimizing personal use days below the threshold that triggers rental property treatment — while documenting maintenance days carefully — allows you to access depreciation and expense deductions. In either case, the strategy must be established before the tax year closes, not reconstructed afterward.
Vacation homeowners who have already accumulated depreciation deductions should model the recapture cost before listing a property for sale, and explore whether installment sale structures or 1031 exchanges could defer that liability.
The IRS does not penalize you for owning a vacation home. It penalizes you for failing to understand which set of rules governs it. Getting that answer right — and acting on it deliberately — is precisely the kind of tax strategy that separates well-advised owners from those who discover the cost only after the fact.